Cafe and Coffee Shop Insurance in Ontario
Your espresso machine, your regulars and your morning rush all depend on the shop staying open. We connect Ontario cafe and coffee shop owners with licensed brokers who build affordable coverage around how small food businesses actually run.
Connect Now
Service & Support:
- Follow-up from a licensed broker within 24 hours
- Policy Review and Comparison
- Risk Assessment
- Help with certificates of insurance, policy changes and contract reviews
- Renewal planning well before your policy expires
Quick answer
What insurance does a cafe or coffee shop need in Ontario?
Most Ontario cafes and coffee shops need commercial general liability, property coverage for equipment and leasehold improvements, equipment breakdown for espresso machines and refrigeration, spoilage, business interruption and cyber for card payments. Cafes that add alcohol, roasting or wholesale need those disclosed. WSIB applies if you have workers.
Coverage built for small, busy spaces
Cafes look low risk, but they combine hot liquids, busy counters, expensive equipment and a lot of foot traffic in a small space. A spilled latte burn, a slip by the door on a snowy morning or a dead espresso machine on a Saturday can all turn into a real cost.
Most cafes can get strong protection at a reasonable price. The key is making sure the policy matches what you actually do: baking on site, roasting, selling packaged beans wholesale, hosting events or adding beer and wine all change the coverage you need.
Connect NowHow CommercialInsurance.ca works
We are not an insurer or a broker. We find you the right one.
Matched by industry
We connect you with a broker who works with businesses like yours, not a generic call centre.
Licensed Ontario brokers
Insurance brokers in Ontario are licensed by the Registered Insurance Brokers of Ontario (RIBO).
Fast follow up
Once we receive your information, a professional in our network will connect with you within 24 hours.
No cost to be matched
Our referral service is free for businesses. You deal directly with the broker for quotes and coverage.
What coverage does a cafe need?
These are the coverages a broker will usually build into a cafe package.
Commercial general liability
Covers customer injuries on your premises, such as burns from hot drinks, slips on a wet floor and trips over a chair, plus food related illness claims and damage to your landlord's property.
- Required by almost every commercial lease
- Covers legal defence as well as damages
- Usually $2 million per occurrence
Equipment breakdown
Espresso machines, grinders, ovens and refrigeration are expensive and easy to lose to an electrical or mechanical failure. Equipment breakdown pays to repair or replace them and can cover lost income while you are down.
- Espresso machines and grinders
- Coolers, freezers and display cases
- Ovens, dishwashers and water systems
Property, stock and spoilage
Covers your furniture, fixtures, leasehold improvements and stock against fire, theft and water damage. Spoilage covers milk, food and baked goods lost when refrigeration fails or the power goes out.
- Leasehold improvements you paid for
- Stock including milk, food and beans
- Power outage and breakdown spoilage
Cyber and payment fraud
Almost every cafe sale is a card tap. Cyber coverage helps if your POS, online ordering or loyalty system is hit by ransomware or a data breach, including the cost of restoring systems and notifying customers.
- POS and online ordering outages
- Customer data breaches
- Read our cyber insurance guide
Cafe risks worth planning for
Roasting and wholesale
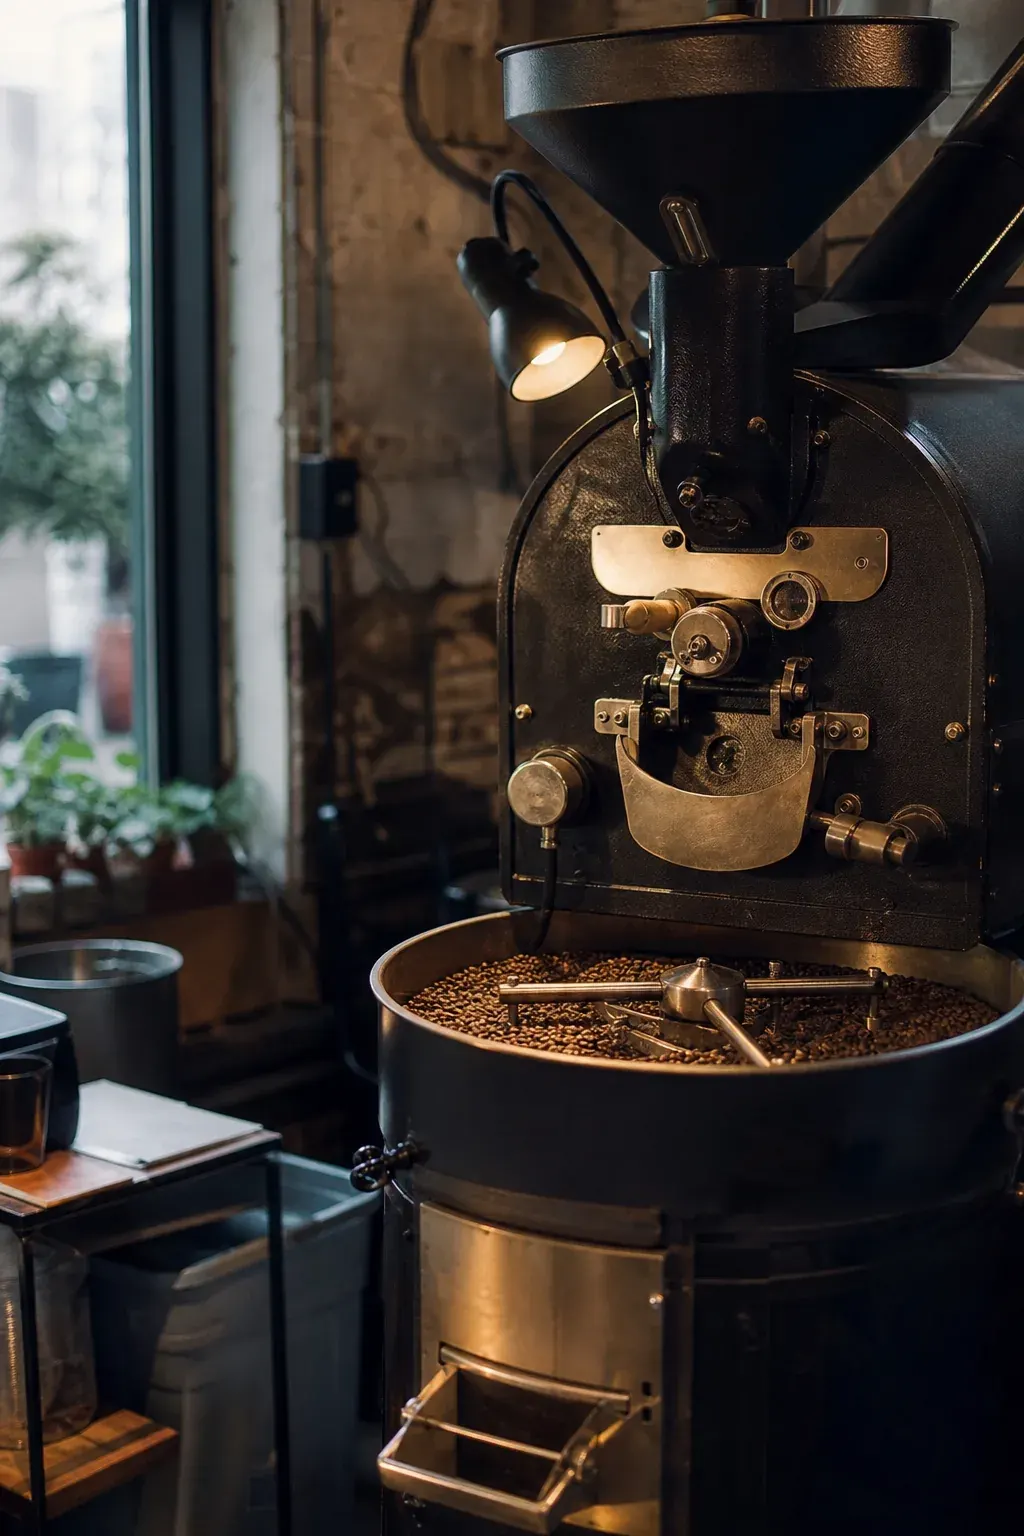
Roasting coffee on site adds fire risk, and selling packaged beans to grocery stores or other cafes adds product liability. Both are insurable, but they must be disclosed so the policy responds.
- Tell your insurer if you roast on site
- Product liability for wholesale and packaged goods
- Keep roaster maintenance records
Winter entrances and patios
Ontario winters make entrances and sidewalks slippery, and a patio adds seating outside your walls. Mats, salt logs and a clear snow clearing agreement with your landlord help prevent claims and show who is responsible.
- Keep a winter maintenance log
- Confirm who clears snow in your lease
- Include patio areas on your policy
What does cafe insurance cost?
Cafes are among the most affordable food businesses to insure. As a general guide, many single location Ontario cafes and coffee shops without alcohol see roughly $1,000 to $3,000 a year for a liability and property package. These are estimates only. See our restaurant insurance cost guide for details.
Keeps costs lower
- No deep frying or open flame
- No alcohol service
- Alarms and good housekeeping
- Claim free history
Adds to the price
- Roasting on site
- Wholesale product sales
- Beer and wine service
- High value equipment
Budget separately
- WSIB for staff
- Cyber coverage
- Commercial auto for delivery vehicles
Protect the shop your regulars love
Tell us about your cafe and we will connect you with a licensed Ontario broker who will build coverage that fits your size, equipment and lease, at a price that makes sense. The referral is free.
Also running a kitchen or bakery? See restaurant insurance and bakery insurance.
Connect NowCafe and Coffee Shop Insurance FAQs
Do I need insurance to open a cafe in Ontario?
No law requires a specific policy for most cafes, but almost every landlord requires commercial general liability and property coverage before you take possession, and WSIB registration is mandatory for most businesses with workers.
Does cafe insurance cover my espresso machine?
Property coverage protects it against fire, theft and water damage. Mechanical or electrical failure needs equipment breakdown coverage, which is well worth adding for expensive machines.
Is a burn from a hot drink covered?
Yes. Customer injuries on your premises, including burns from hot drinks, fall under commercial general liability.
What if I start selling beer and wine?
You will need a liquor sales licence and your insurer must add liquor liability. Tell your broker before you start serving.
Do I need product liability if I sell packaged coffee?
If you sell packaged beans, baked goods or other products to other businesses or retailers, make sure your policy includes products and completed operations coverage.
How much does cafe insurance cost?
Many single location cafes without alcohol see roughly $1,000 to $3,000 a year for a liability and property package. That is an estimate; your actual premium depends on your equipment, sales, location and claims history.
What happens after you request commercial insurance?
 1
Discovery Call
(30 to 45 min)Understand operations, contracts, assets, and loss history.
Get Started Now!
We will request your
expiring policies and loss runs. 2
Risk Mapping
(1 to 3 days)Document exposures, limits, sublimits, deductibles, and endorsements that fit your contracts.
Get Started Now! 3
Market Placement
(2 to 5 days)Approach the right markets
Get Started Now!
and negotiate terms, exclusions, and deductibles. 4
Proposal & Bind
Get Started Now!
Side-by-side options in clear wording, so you can choose with confidence.
Protect your team too
Offer health, dental and life benefits your employees will value.
We also connect Ontario businesses with licensed benefits advisors, from two person teams to growing companies.
 5/5 rating on Google
The Commercial Insurance Difference: Feedback from those referred
Proactive Broker Relationship.
The most noticeable difference was the fact that I no longer felt that I was needed to manage the broker... the brokers came to me with proactive recommendations and knew when to push and shop the market and when not to. When the topic of business insurance comes up, I always refer fellow business owners.
Steve T
Security Blanket For My Business
I was always the type of customer that never believed in insurance and only really got it because I had to. Then I connected with a broker through Commercial Insurance.ca and they asked me questions no one else ever did and that's how I knew something was different. They took the time to understand and evaluate the risks. Well, I ended up getting some extra coverage (legal expense) and thank goodness I did. Something fairly innocent turned into something quite nasty and I didn't have to do too much... my coverage took care of it. Now I look at Insurance as a security blanket for my business.
Michael L
They had my back
No one likes buying insurance because it's a bit of a bet against yourself. You just hope that when the bad things happen that insurance will do what it said it would do in the first place. Their specialist stand behind the policy's that they bind. They never professed to get me the best price, but they did say they have my back, and have my back, they did.
Steph P