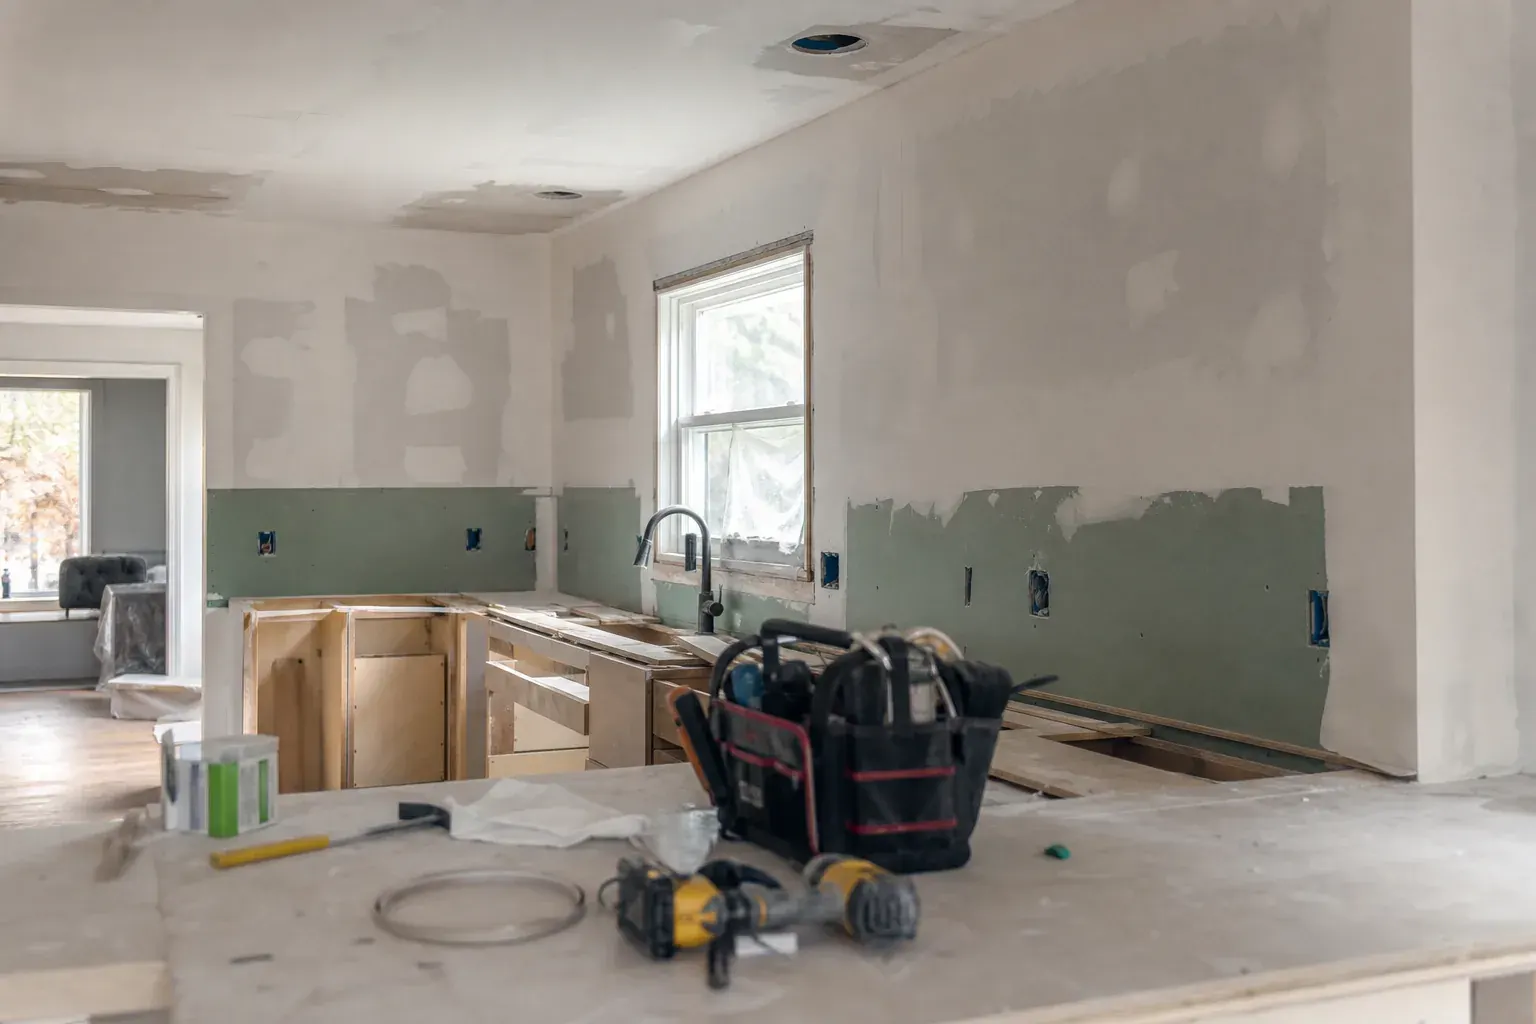
Renovation contractor insurance when the job is inside someone's home
Renovations happen in people's homes, often while they live there. That means their floors, belongings and families are part of your job site. We connect Ontario renovators with licensed brokers who build coverage for occupied homes and the contracts homeowners now expect.
Connect Now
Service & Support:
- Follow-up from a licensed broker within 24 hours
- Policy Review and Comparison
- Risk Assessment
- Help with certificates of insurance, policy changes and contract reviews
- Renewal planning well before your policy expires
Quick answer
What affects the cost of renovation contractor insurance?
Renovation contractor insurance cost is driven by the type of work you take on, your annual revenue and payroll, how much hot work and structural work you do, your use of subcontractors and your claims history. Working in occupied homes and condos, adding builder's risk or installation floater coverage for larger projects, and carrying higher liability limits all add to the premium. WSIB and commercial auto are priced separately.
Why does working in occupied homes change the risk?
Working in an occupied home raises the risk because renovation claims often involve damage to the parts of the home you were not working on: a water line nicked while opening a wall, dust through the HVAC system, or a fire from hot work. Homeowners and their insurers expect you to carry the right coverage, and many will ask to see it before signing.
In Toronto, businesses that repair or renovate buildings, including those that advertise renovation services, need a City of Toronto building renovator licence. WSIB rules also matter: independent operators doing home renovation work hired directly by the homeowner are exempt from mandatory coverage, but anyone with workers must register.
Connect NowHow CommercialInsurance.ca works
We are not an insurer or a broker. We find you the right one.
Matched by industry
We connect you with a broker who works with businesses like yours, not a generic call centre.
Licensed Ontario brokers
Insurance brokers in Ontario are licensed by the Registered Insurance Brokers of Ontario (RIBO).
Fast follow up
Once we receive your information, a professional in our network will connect with you within 24 hours.
No cost to be matched
Our referral service is free for businesses. You deal directly with the broker for quotes and coverage.
What coverage does a renovation contractor need?
A renovation contractor needs commercial general liability with completed operations, tools and equipment coverage, commercial auto and, on larger projects, builder's risk or an installation floater for work in progress. These are the coverages a broker will usually build into a renovator's program.
General liability with completed operations
Covers damage to the client's home and belongings and injuries to anyone on site, plus claims that arise after completion, such as a leak from a new bathroom.
- Damage to existing structure and contents
- Completed operations after handover
- Certificates for homeowners and condo boards
Builder's risk or installation floater
On larger renovations, the new work and materials can be damaged by fire, theft or weather before completion. Homeowner policies may not cover it, so an installation floater or renovation builder's risk policy fills the gap.
- Materials on site before installation
- Work in progress
- Coordinate with the homeowner's insurer
Tools and equipment
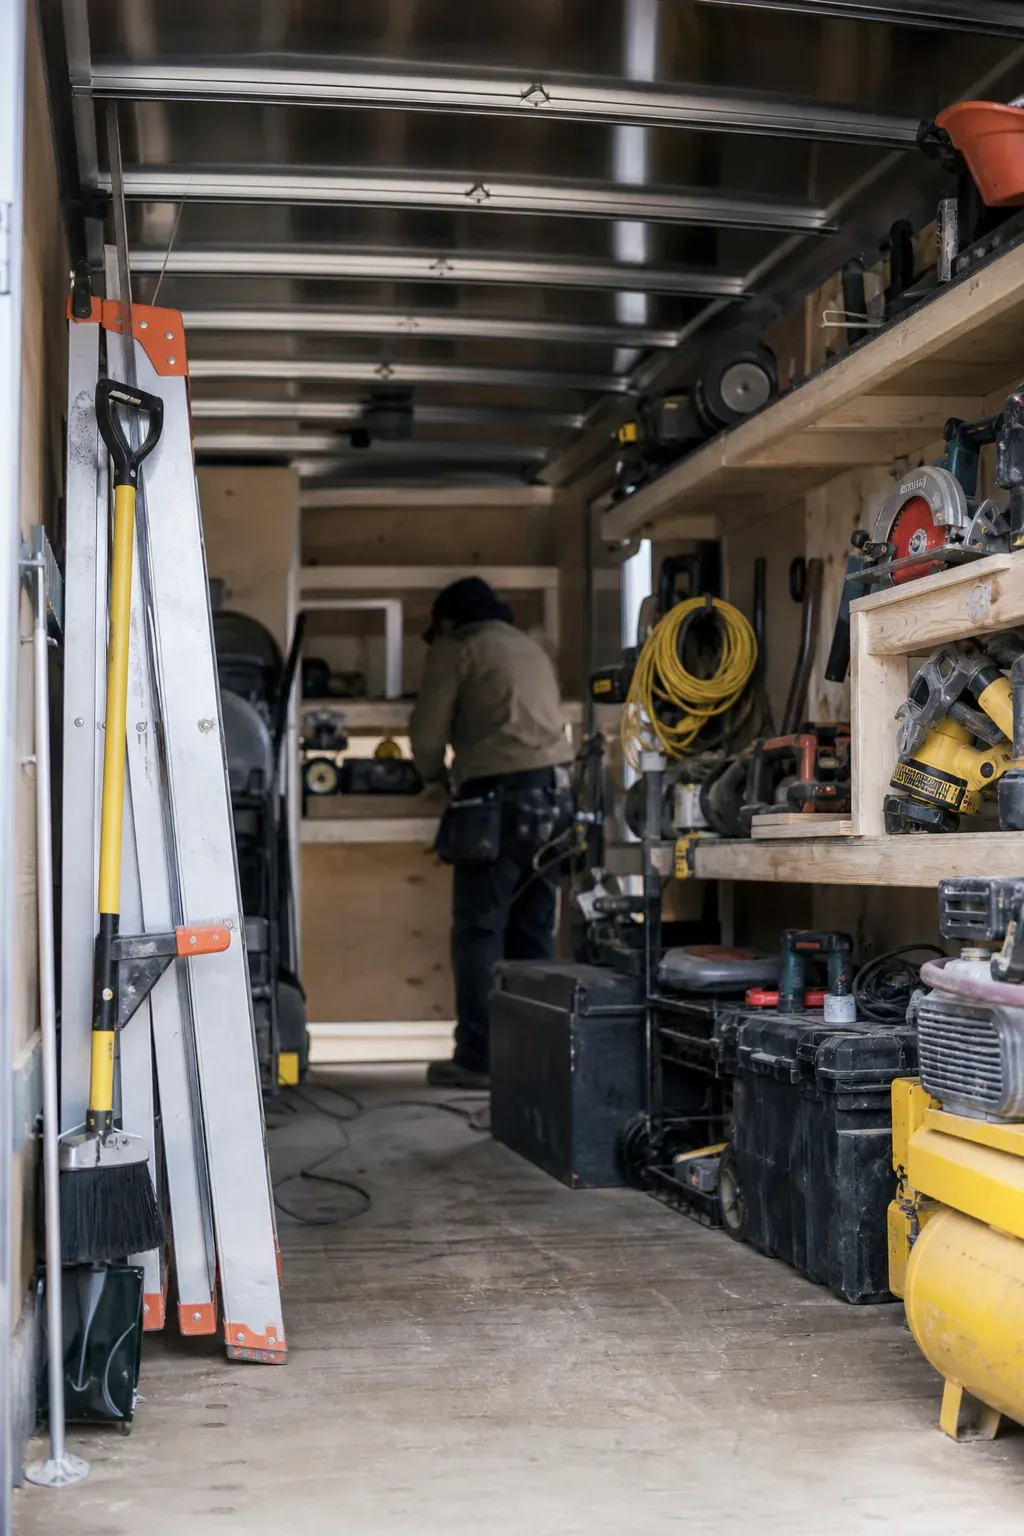
Tools and trailers are frequent theft targets at renovation sites. Coverage should follow them on site, in transit and in storage.
- Tools and trailers
- Rented equipment
- Theft from vehicles
Renovation risks worth planning for
Kitchens and bathrooms
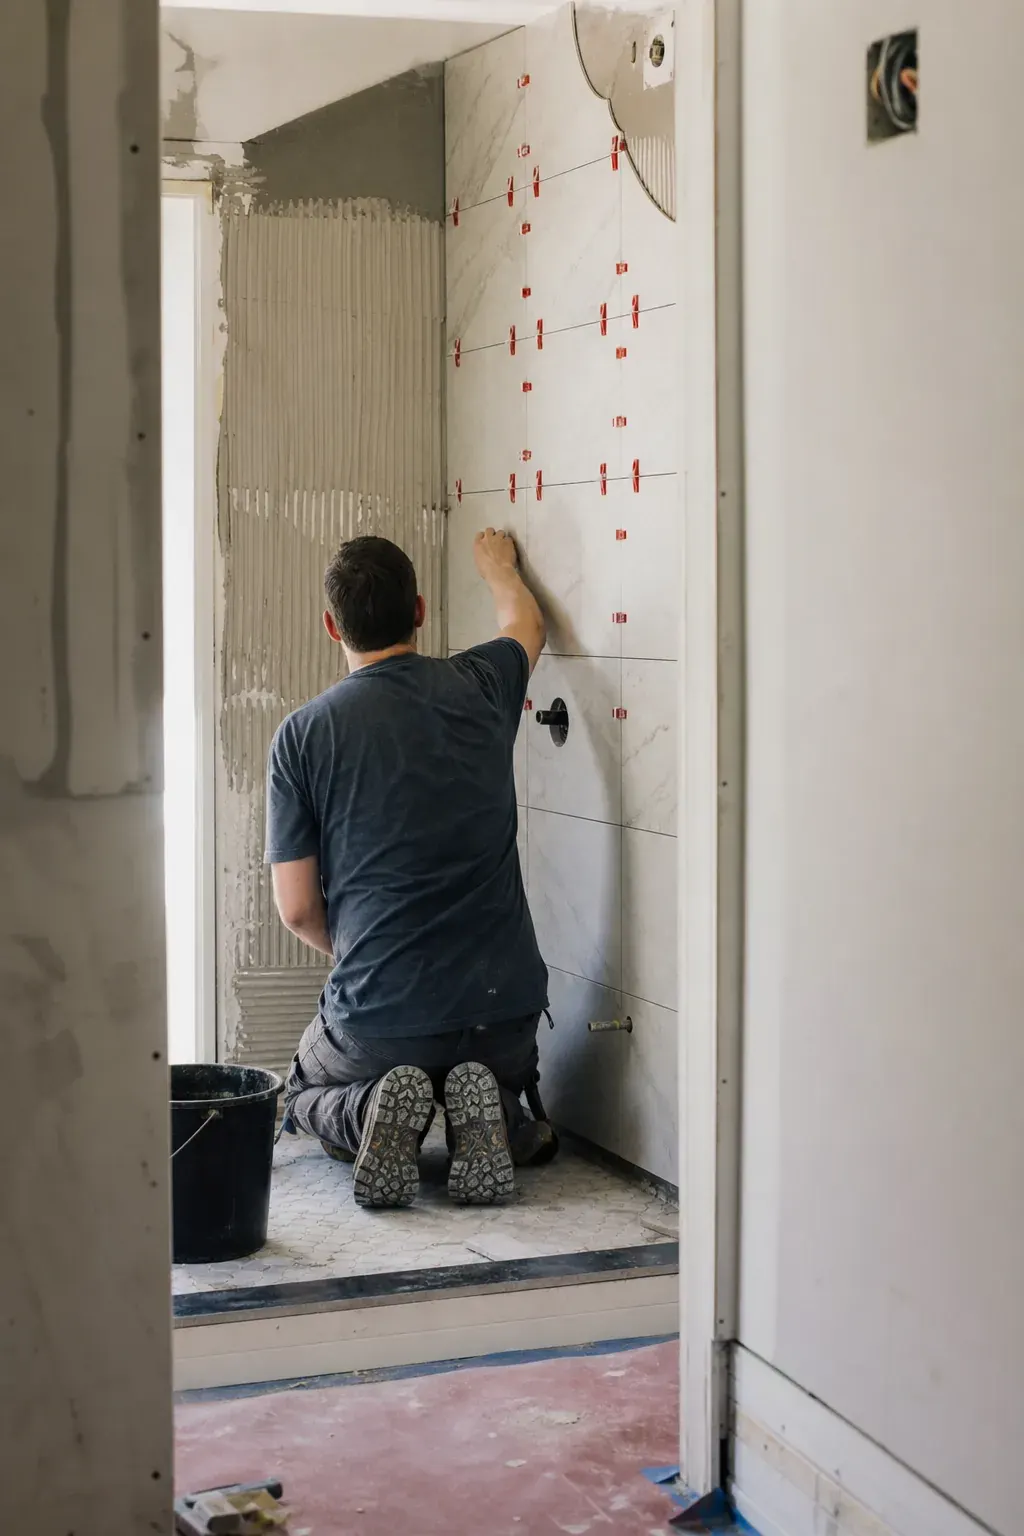
Kitchens and bathrooms combine plumbing, electrical and finishes in small spaces. Use licensed trades for plumbing and electrical, pull permits when required and document every stage with photos.
- Licensed subs for plumbing and electrical
- Permits and inspections
- Photos before closing walls
Condo renovations
Condo boards usually require a certificate of insurance with the corporation named as an additional insured, plus rules on working hours, elevators and water shut offs. Water damage in a condo can reach several units.
- Condo corporation as additional insured
- Follow building rules and shut off procedures
- Disclose condo work to your insurer
What does renovation contractor insurance cost in Ontario?
As a general guide, many Ontario renovation contractors running as an owner operator or small crew see roughly $1,500 to $6,000 a year for $2 million in general liability plus tools and equipment coverage. WSIB and commercial auto are priced separately. These are estimates only. See our contractor insurance cost guide.
Raises the price
- Structural and additions work
- Condo renovations
- Heavy subcontracting
- Past water or fire claims
Helps lower it
- Licensed subs with certificates
- Permits and documentation
- Clean claims history
- Several years in business
Budget separately
- WSIB premiums, based on insurable earnings
- Commercial auto for work vehicles
- Surety bonds for bonded contracts
Give homeowners proof and protect your business
Tell us about your renovation business and we will connect you with a licensed Ontario broker who understands occupied home and condo work and can issue certificates for your next client quickly.
Smaller repair jobs? See handyman insurance.
Connect Now
Renovation Contractor Insurance FAQs
Do I need a licence to be a renovator in Toronto?
A building renovator licence is required by the City of Toronto for businesses that repair or renovate buildings, including those that advertise renovation services. It involves an application, fees and an oral trade exam.
Does renovation insurance cover damage to the client's home?
Commercial general liability covers damage you cause to the client's property, but not the cost of redoing your own faulty work. Check how your policy handles damage to the part of the home you were working on.
Do renovators need WSIB?
Most construction businesses must have WSIB. Independent operators who only do home renovation work hired directly by homeowners are exempt, but if you have workers you must register.
Who insures the renovation work before it is finished?
An installation floater or renovation builder's risk policy insures materials and work in progress, because the homeowner's policy may not. Agree who is responsible in your contract.
How fast can I get a certificate of insurance for a new job?
A broker who works with contractors can usually issue a certificate of insurance the same day, including additional insured wording for the general contractor or property owner. See our certificate of insurance guide.
How does a renovation contractor get quoted?
After you request commercial insurance, a licensed Ontario broker reviews your request and follows up within 24 hours to confirm your details and start quoting.
 1
Discovery Call
(30 to 45 min)Understand operations, contracts, assets, and loss history.
Get Started Now!
We will request your
expiring policies and loss runs. 2
Risk Mapping
(1 to 3 days)Document exposures, limits, sublimits, deductibles, and endorsements that fit your contracts.
Get Started Now! 3
Market Placement
(2 to 5 days)Approach the right markets
Get Started Now!
and negotiate terms, exclusions, and deductibles. 4
Proposal & Bind
Get Started Now!
Side-by-side options in clear wording, so you can choose with confidence.
Protect your team too
Offer health, dental and life benefits your employees will value.
We also connect Ontario businesses with licensed benefits advisors, from two person teams to growing companies.
 5/5 rating on Google
The Commercial Insurance Difference: Feedback from those referred
Proactive Broker Relationship.
The most noticeable difference was the fact that I no longer felt that I was needed to manage the broker... the brokers came to me with proactive recommendations and knew when to push and shop the market and when not to. When the topic of business insurance comes up, I always refer fellow business owners.
Steve T
Security Blanket For My Business
I was always the type of customer that never believed in insurance and only really got it because I had to. Then I connected with a broker through Commercial Insurance.ca and they asked me questions no one else ever did and that's how I knew something was different. They took the time to understand and evaluate the risks. Well, I ended up getting some extra coverage (legal expense) and thank goodness I did. Something fairly innocent turned into something quite nasty and I didn't have to do too much... my coverage took care of it. Now I look at Insurance as a security blanket for my business.
Michael L
They had my back
No one likes buying insurance because it's a bit of a bet against yourself. You just hope that when the bad things happen that insurance will do what it said it would do in the first place. Their specialist stand behind the policy's that they bind. They never professed to get me the best price, but they did say they have my back, and have my back, they did.
Steph P